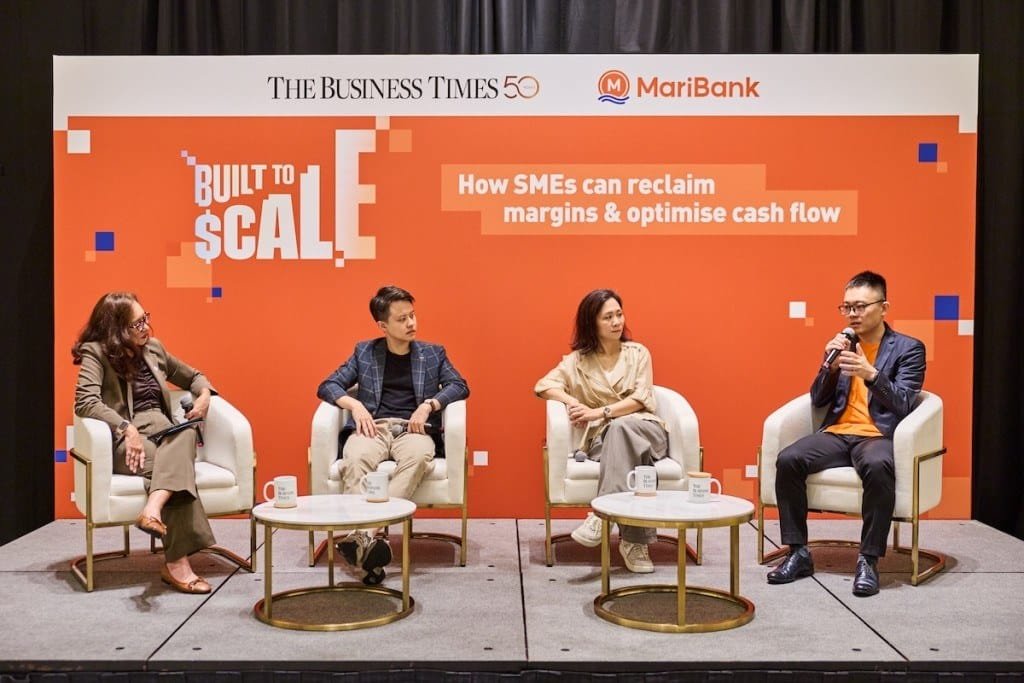
Revenue growth is only half the story for small and medium enterprises. The other half — the part that quietly erodes the bottom line — is the money that leaks out through fees, slow banking processes and administrative drag that few owners stop to measure. At a panel event co-organised by digital bank MariBank and The Business Times in Singapore on 15 October 2026, three business leaders made the case that fixing those leaks may matter more to long-term SME health than chasing the next contract.
The Hidden Drain That Compounds Quietly
The panel discussion — titled “Built to Scale: How SMEs Can Reclaim Margins and Optimise Cash Flow” — centred on what the speakers called the “leaky bucket”: the accumulation of small, unmonitored costs that most SMEs do not actively track. Rent, payroll and raw materials get watched closely; account maintenance fees, foreign-exchange markups on overseas transfers, minimum-balance penalties and per-transaction charges typically do not.
Tan Yee Hern, assistant managing director at Capstone Aluminium, described the tension plainly. “We’ve got many things to manage and look at. It’s only inevitable that we have some leaks here and there. Account fees, FX exchange, your transaction costs and all that — all of these add up,” he said at the event.
Sharon Teo, CEO and co-founder of Inspire-Tech, pointed to a structural disadvantage that makes the problem worse: smaller businesses simply lack negotiating leverage. “Because we don’t have the volume … you’re not really in that position. So you are always the price taker. Whatever is given to you, you just take it,” she explained. Minimum-balance requirements in particular frustrated her in Inspire-Tech’s early years, when cash flow was already stretched. “Sometimes, seeing that we are almost reaching or we are below that balance … actually distracts us from doing business,” she said.
Time as the Costlier Resource
The panel’s more striking argument was that slow processes cost SMEs more than fees do. Tan described what happened to Capstone Aluminium during the Covid-19 pandemic, when construction continued in Singapore and his company faced fewer supply-chain constraints than competitors. Capstone accepted two, three or four times its usual project load — but needed capital quickly to procure the raw materials.
The problem: in the construction sector, payment typically comes at least 180 days after work is completed. Capstone needed loans immediately, and working through traditional banks took months — in some instances, close to a year. “If you don’t have speed, you don’t have efficiency. You might just miss the boat, right?” Tan said. Capstone eventually secured the financing it needed, but Tan noted that only the multi-year nature of construction contracts gave the company enough breathing room. A business operating on shorter cycles might have lost those opportunities entirely.
Teo introduced a related point about internal time costs. If a staff member spends a full day completing a banking or administrative task to save the company US$50, the net result is likely negative. “Sometimes we can be penny wise but pound foolish,” she said. The mental load of paperwork also carries a cost: “It eats away at our mental capacity and our load. That distracts us from our business, which I feel is even more costly than the monetary cost,” Tan added.
MariBank’s Model: Build From Scratch, Not Patch
Tiger Wang, Monee consulting director for SME business solutions at MariBank Singapore, used the event to explain the structural argument for digital banking. Because digital banks are not retrofitting decades-old systems, they can redesign processes rather than work around them. “We have a chance to rebuild all these processes from scratch and use technology to make a lot of these processes faster,” he said.
MariBank’s current offer for SMEs, as described by Wang at the event, eliminates account maintenance fees and foreign-exchange markups on overseas remittances, and pays daily interest on deposit balances. On lending, the bank uses tools to digitise the reading of bank statement submissions and auto-generate data for credit assessors, compressing the underwriting timeline. Wang also referenced revolving credit facilities where interest is charged only when the borrower actually draws on the loan — a structure that reduces idle interest costs for businesses with variable capital needs.
Tan confirmed from experience that digital banks moved materially faster on loan applications during the pandemic period: in at least one case, a digital bank had already disbursed funds before a traditional institution finished processing his application.
MariBank is a wholly owned subsidiary of Sea Limited and operates in Singapore under Monee, formerly known as SeaMoney. The bank is supported by its ecosystem partner Shopee. These are facts stated in the source material; independent financial or regulatory details about MariBank are not stated in the supplied sources.
The Adoption Gap: Speed Is Not Enough
Audience questions at the 15 October event surfaced a consistent hesitation: SME owners want speed and lower fees, but they are not ready to give up the ability to speak to a person when something goes wrong. Chatbots and automated systems are acceptable for routine transactions; they are not, in the audience’s view, an adequate substitute for human judgement on complex issues. Physical branches also carry a trust signal that digital-only operations have not yet replicated.
Wang acknowledged the gap directly. “Trust will be gained through consistently delivering reliable services to our customers, being there on time, minimal downtime to our systems, and being always responsive to the queries from the customers,” he said. He offered no shortcut: for digital banks, the path to trust runs through operational reliability, not marketing.
What SMEs and Digital Banks Both Have to Prove
The panel’s conclusion — implicit rather than stated as a formal recommendation — was that the choice is not between traditional banks and digital ones. It is about which combination of tools lets an SME stop haemorrhaging money through fees and administrative drag while maintaining the relationships and safeguards that larger capital decisions require.
That framing puts two sets of actors under pressure. SMEs need to treat time and process efficiency as measurable cost lines, not soft concerns. Digital banks need to earn trust incrementally through uptime, response speed and loan delivery — not by asking SME owners to take their technology on faith.
Whether platforms like MariBank can close the trust deficit at scale while keeping fee structures genuinely lower than legacy competitors is the number worth watching. The commercial model only holds if the cost savings reach SME owners in practice, not just in product descriptions.