Xendit spent its first five years building payment infrastructure in Indonesia before moving into a single new market. That restraint is now the foundation of a regional expansion spanning seven markets — and the logic behind it offers a clear lesson for any startup thinking about scaling across Southeast Asia.
The Idea: Infrastructure Before Expansion
Founded in Indonesia in 2015, Xendit set out to help businesses collect payments, make payouts, and manage transactions. The idea was not simply to build a payment gateway for one market — it was to create a platform flexible enough to absorb whatever each market threw at it.
Indonesia gave Xendit an unusual proving ground. When the company launched, cash was still the dominant way most Indonesians paid. Over the following years the landscape shifted quickly: e-wallets from companies such as Ovo and Dana gained traction, real-time payments arrived, and the Quick Response Code Indonesian Standard changed point-of-sale habits across the country. Xendit chose to keep pace with every change rather than lock itself into a single method.
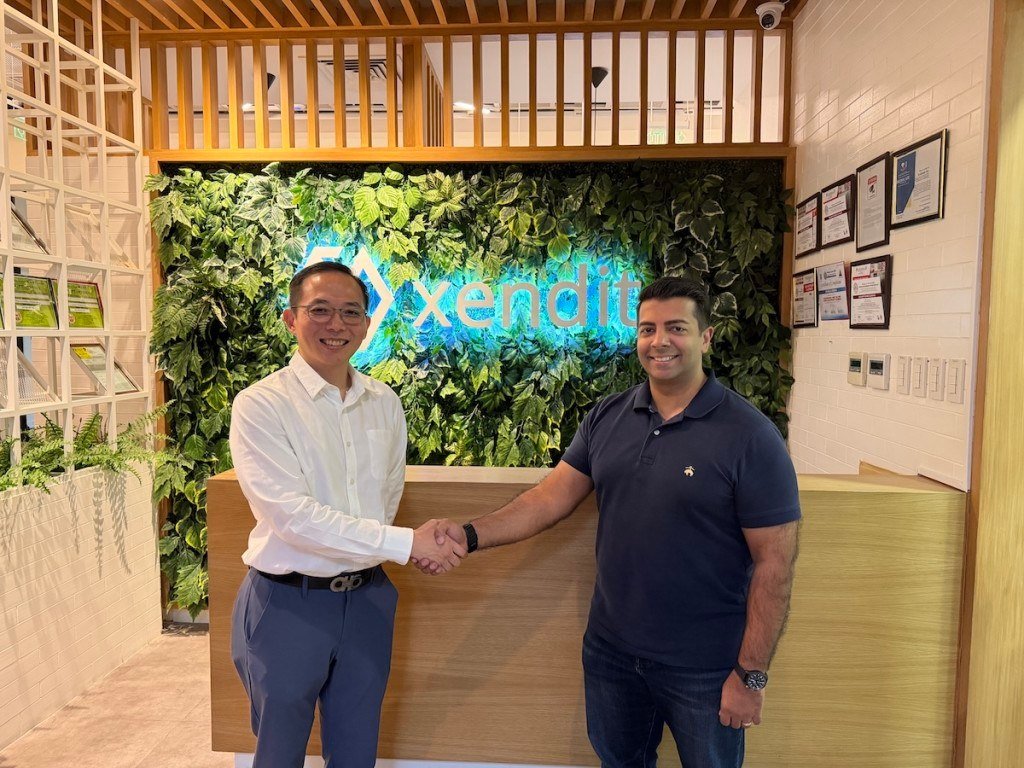
“That amount of flexibility and versatility means that when you go into a new market, you have that infrastructure in place,” says Nazim Ali, Xendit’s president, as quoted in a paid content partnership published by Tech in Asia on 26 October 2026.
The Problem: Southeast Asia’s Payments Complexity Is a Barrier Most Companies Don’t Cross
For global and regional companies wanting to operate across Southeast Asia, the payments landscape is a genuine obstacle. Each market has its own regulators, its own dominant payment methods, and its own consumer habits. A company that solves collections in Indonesia may find none of that infrastructure transfers to the Philippines or Malaysia.
The Philippines illustrates the scale of the problem. It has more than 100 million people, a young population, and more mobile phones in circulation than there are residents — yet the payments complexity of that market had not been addressed by the time Xendit arrived in 2020, according to Ali’s account in the same article.
For global businesses, the hesitation is similar. Many see Southeast Asia as a growth opportunity but stall when they encounter the region’s mix of markets, regulators, and payment methods operating in parallel.
The Business Model: Acquire Local Knowledge, Then Layer Your Own Platform on Top
Xendit’s entry strategy combines acquisition of established local operators with the simultaneous setup of its own licensed business. The company applied this approach in both of the markets where it made acquisitions.
When it entered the Philippines in 2020, Xendit acquired Dragonpay, a local payments company with existing infrastructure and market knowledge, while also opening its own office, securing a payments licence, and signing up customers directly. The dual approach gave Xendit local operational depth without abandoning the product principles it had built in Indonesia.
In Malaysia, which Xendit entered in 2023, it invested in and later acquired payment gateway Payex, applying the same blended model. The company has since expanded into Thailand, Vietnam, Singapore, and Hong Kong — its most recent market as of the article’s publication date.
Clients named in the source article include regional tech companies Grab and Traveloka, and global brands Meta, ByteDance, Allianz, Levi’s, and Starbucks. These are company claims as reported in the Tech in Asia content partnership; independent verification of client relationships is not available in the supplied sources.
Xendit’s revenue model — transaction processing and payouts for businesses — is not broken down by market or product line in the supplied sources.
Growth: How a Strong Core Platform Creates Compounding Returns
Ali describes the expansion pace as a function of what was built first. A well-constructed core platform, in his framing, produces compounding returns: each new market takes less time to enter than the one before because the infrastructure, the regulatory track record, and the organisational muscle already exist.
“If you’ve built a very good core platform, you have the ability to have this compounding return in terms of the muscle you’ve built for international expansion,” he says in the source article. “The pace at which you look into new markets can be much quicker.”
The company also points to its regulated status in Indonesia as an asset in subsequent markets. Operating in a tightly regulated environment from the start gave Xendit a track record that made conversations with regulators, partners, and merchants in new markets more straightforward, according to Ali.
People strategy is a second growth variable the company treats as non-negotiable. Ali flags the tension between bringing in local hires who understand the market and retaining the institutional knowledge of existing staff — a balance that Xendit treats as deliberate rather than incidental.
A third discipline that emerged through expansion was resisting short-term distractions. Early-stage pilots and one-off customer wins can generate learning, Ali says, but Xendit developed a rule of always checking whether smaller projects were pulling focus away from the core product roadmap.
What Comes Next for Xendit
Ali is explicit that the current seven-market footprint is not a stopping point. More markets in Asia Pacific are on the roadmap, though no specific countries or timelines are stated in the supplied sources.
Two areas of product development are named: agentic AI and agentic finance, and stablecoins. The company is described as exploring both as ways to broaden what its payments platform can do, though no product launches, integration details, or commercial timelines are provided in the source material.
The clearer near-term opportunity, based on what Ali describes, is helping global companies navigate the region’s complexity from a single integration point. If Xendit can credibly serve as that layer — handling collections, payouts, licences, and local payment method variety across multiple markets — the addressable market grows every time another global brand decides Southeast Asia is worth the entry effort.
What makes Xendit’s trajectory worth watching is not the speed of its expansion but the sequence: build the platform, earn the regulatory trust, acquire local knowledge, and only then accelerate. That order of operations is the actual innovation — and it is one that most fast-moving fintech entrants choose to skip.